Top Software Companies in Bengaluru (781)
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at a strong double‑digit pace with Cloud accelerating, while forward indicators like ARR and contracted backlog are also expanding, pointing to durable top‑line momentum.
Innovation-Driven Growth: AI-led capabilities (e.g., Rovo) and deeper platform adoption are tied to higher monetization and faster ARR expansion among adopters, reinforcing product-led growth.
Customer Loyalty & Retention: Cloud net revenue retention remains well above 100% and has improved over successive quarters, suggesting healthy expansion within the existing customer base.
We are a mobility company that innovates like a start-up and thinks like a technology company. This helps us anticipate change in one of the most complex industries in the world and respond quickly. We depend on a team of 171,000 dynamic, entrepreneurial-minded employees in an environment where great ideas flourish. Our presence spans 343 manufacturing operations and 88 product...

Magna International's Top Stability & Growth Strengths
Profitability: Q2 2026 results show adjusted EBIT up 16%, margin up 70 bps to 6.2%, and adjusted EPS up 29% to a Q2 record $1.86. Following Q2, management raised the 2026 adjusted EPS outlook, signaling confidence in continued margin expansion.
Healthy Cash Flow: Free cash flow more than doubled year over year to $617M in Q2 2026, reaching $989M for the first half. The full-year 2026 outlook calls for approximately $1.75–$1.85B of free cash flow.
Cost & Operational Efficiency: Cost actions and productivity improvements are expanding margins and boosting earnings. Mix shift toward higher‑margin programs and recent wins support organic growth into future periods.

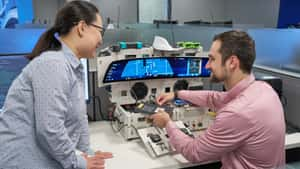
At General Motors, our vision is to create a world with Zero Crashes, Zero Emissions, and Zero Congestion. We wholeheartedly embrace the responsibility to lead the change that will make our world better, safer, and more equitable for all. Our industry and company are undergoing a once-in-a-lifetime technological transformation, which is reshaping our approach to technology and innovation. We are expanding...
General Motors's Top Stability & Growth Strengths
Profitability: Profit metrics and margins are rising in 2026, with Q2 EBIT‑adjusted up ~30% to $3.94B and the margin improving to 8.2%, alongside a first‑half margin of 8.9%. Management also raised full‑year 2026 profit guidance to $14–$16B, reflecting stronger earnings power driven by mix, pricing, and cost discipline.
Healthy Cash Flow: Adjusted automotive free cash flow grew sharply (up 78% in Q2 and 73% year to date), and the company reinforced confidence by declaring a $0.18 quarterly dividend and authorizing a $6B buyback. These capital returns accompany higher full‑year free‑cash‑flow guidance of $9.5–$11.5B.
Diversified Revenue Streams: Software‑enabled services and subscriptions are contributing more meaningfully, with roughly 620,000 subscribers, $5.4B of deferred revenue at 2025 year‑end, and OnStar revenue up ~20% year over year in Q2 2026. The company indicates software revenue is on track to exceed $3B in 2026.
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Q2 2026 total net revenue rose 4% sequentially to $15.9 billion. Integration of Discover and Brex contributed to higher non‑interest income and broader payments capabilities.
Profitability: Q2 2026 net income reached $3.0 billion, up from $2.2 billion in Q1 2026, alongside a net interest margin of 8.01%. Management also cited strong credit performance, including a $662 million reserve release.
Market Expansion: Acquisition‑driven scale is broadening reach, with the Discover deal (closed May 18, 2025) and Brex (closed April 7, 2026) adding network and corporate card/spend‑management capabilities. Balance‑sheet growth continued in Q2 2026 as period‑end loans rose 2% to $457.2 billion and total assets reached $673.8 billion.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 23% year over year in Q2 2026 and 24% for full-year 2025, with ARR up 25% and GPV up 22% reinforcing a scaling top line. Guidance for 2026 recurring gross profit growth of roughly 23–25% further underpins momentum.
Profitability: Operating income and EPS roughly doubled year over year in Q2 2026 (operating income $152M vs. $80M; diluted EPS $0.26 vs. $0.13). Management also highlighted rising adjusted EBITDA and improved net income alongside recurring gross profit expansion.
Market Expansion: New offerings (e.g., Toast Drive‑Thru) and enterprise wins/expansions (e.g., Best Western, TGI Fridays UK, multi‑unit brands like Caribou Coffee and Potbelly) support broader adoption. The footprint reached about 180,000 total locations as of June 30, 2026, up roughly 22% year over year.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue has increased over consecutive fiscal years to $638.4 million in FY26, building on gains reported in FY24 and FY25. This points to continued top-line expansion.
Investor Backing & Capital Strength: A significant minority investment from New Mountain Capital was announced on August 1, 2025 to accelerate growth, technology and acquisitions under an alternative practice structure. This provides funding capacity to scale and pursue M&A.
Innovation-Driven Growth: The mix is shifting toward advisory and technology services (nearly half of revenue per the firm), with capability additions reinforcing this pivot. The CompliancePoint transaction further broadens cybersecurity, privacy and compliance offerings.
Zeta Global (NYSE: ZETA) is the AI Marketing Cloud that leverages advanced artificial intelligence (AI) and trillions of consumer signals to make it easier for marketers to acquire, grow, and retain customers more efficiently. Through the Zeta Marketing Platform (ZMP), our vision is to make sophisticated marketing simple by unifying identity, intelligence, and omnichannel activation into a single platform –...
Zeta Global's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating with multiple raised full‑year outlooks and consecutive quarters of rapid top‑line increases. The business also highlights a long “beat and raise” cadence into 2026.
Profitability: GAAP net income turned positive in 2026 alongside expanding adjusted EBITDA. Management continues to guide to improved margins through the year.
Healthy Cash Flow: Free cash flow is rising and full‑year cash generation guidance was increased. Disclosures point to stronger operating cash flow through the first half of 2026.
At eClinical Solutions, our goal is to leverage technology to accelerate clinical research and bring life-changing therapies to patients faster. Our industry-leading elluminate® clinical data platform is used by top life sciences companies worldwide to regain control of their data and provide meaningful analytical insights.
eClinical Solutions's Top Stability & Growth Strengths
Strong Revenue Growth: Reported year-over-year software growth in 2024, alongside multi-year increases and net new client additions, indicates sustained commercial momentum. Customer penetration among large pharma is described as expanding across 2024–2025.
Investor Backing & Capital Strength: A majority investment by GI Partners, with Summit Partners remaining a minority investor, is described as supporting further scale, product investment, and global reach. This signals access to resources for continued expansion.
Strong Market Position & Advantage: Independent recognition as the highest-designated Leader in 2024 for life sciences clinical data and analytics platforms, coupled with adoption by numerous top biopharma companies, signals competitive strength in its core segment. Named client expansions further reinforce visibility and impact.
.png)
Navan (Nasdaq: NAVN) is the leading all-in-one business travel, payments, and expense management platform that makes travel easy for frequent travelers. From finding flights and hotels to automating expense reconciliation, with 24/7 support along the way, Navan delivers an intuitive experience travelers love and finance teams rely on. See how Navan customers benefit and learn more at navan.com.

Navan's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue grew 31% to $702M in FY2026, then accelerated to 40% year over year in Q1 FY2027, with full‑year FY2027 revenue outlook raised to roughly 30% growth. Momentum is reinforced by expanding enterprise adoption and integrations that support usage growth.
Profitability: FY2026 marked the first full year with positive non‑GAAP operating income alongside positive operating and free cash flow, and Q1 FY2027 non‑GAAP operating margin reached 11%. These milestones indicate improving operating leverage as scale increases.
Cost & Operational Efficiency: AI agent automation (e.g., Ava handling about 52% of interactions in FY2026) is underpinning service scalability and margin expansion. Further increases in AI‑handled interactions are expected to support additional efficiency gains.

Celonis makes processes work — for people, companies, and the planet. Powered by process mining and AI, the Celonis Process Intelligence Platform integrates process data and business context to create a living digital twin of business operations. We enable thousands of companies worldwide to understand how their business actually runs and, together with their partners, build intelligent solutions that transform...

Celonis's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent market-share analysis places Celonis at the front of its category while the market itself expands. This positioning suggests the company is capturing growth in a segment it leads.
Future-Ready Strategy: External recognition for long-term growth potential signals confidence in Celonis’s strategy, innovation, and talent pipeline. This points to preparedness as the space broadens from process mining into process intelligence and AI-enabled workflows.
Strategic Partnerships: A new alliance with a major data and AI platform provider expands product integrations and go-to-market reach into enterprise AI workflows. Such ecosystem momentum supports broader adoption and commercial expansion.
Headquartered in New York City, Take-Two Interactive Software, Inc. is a leading developer, publisher, and marketer of interactive entertainment for consumers around the globe. We develop and publish products principally through Rockstar Games, 2K, and Zynga. Our strategy is to create hit entertainment experiences, delivered on every platform relevant to our audience through a variety of sound business models. Our...
Take-Two Interactive Software's Top Stability & Growth Strengths
Strong Revenue Growth: GAAP net revenue rose 18% to $6.66 billion in FY2026, and an initial FY2027 net bookings outlook of $8.0–$8.2 billion implies further scale. In Q1 FY2027, GAAP net revenue also increased year over year and bookings slightly exceeded guidance.
Diversified Revenue Streams: Live services and in‑game purchases comprised the majority of Q1 FY2027 revenue and bookings, helping to smooth results between major releases. The expanded mobile footprint following the Zynga acquisition adds a meaningful second pillar beyond premium console/PC titles.
Future-Ready Strategy: Management has tied FY2027 scale to the November 19, 2026 launch of Grand Theft Auto VI while reaffirming bookings guidance. A successful release is positioned to materially lift results.
Enverus’ innovative technologies drive production and investment strategies, enable best practices for energy and commodity trading and risk management, and reduce costs through automated processes across critical business functions. Enverus is a strategic partner to more than 6,000 customers in 50 countries. Enverus is a portfolio company of Hellman & Friedman and Genstar Capital.
Enverus's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue scale is signaled by surpassing $500M in annual recurring revenue in July 2023, creating a high base for subsequent expansion. Company communications frame later moves as building on this milestone.
Market Expansion: Recent acquisitions—Spatial Business Systems, PDS Energy’s exchange platforms, and TGS’s A2D well log library—extend reach into utilities engineering, operational exchanges, and subsurface data. Solutions marketed across upstream, midstream, power and renewables point to a broadening footprint.
Investor Backing & Capital Strength: Blackstone agreed in August 2025 to acquire Enverus in a deal reported at $6.5B+ and later referenced deploying capital into the company in 1Q26. This indicates substantial resources and conviction to support further scaling.

CWAN was founded on a simple belief: investment professionals deserve modern technology that actually works for them. Not legacy systems that slow them down. Not fragmented data that creates confusion. But one comprehensive platform that gives you complete visibility and crystal-clear insights. The result? Investment management that works as seamlessly as your investment strategy. Since our founding in 2004, CWAN has been...

Clearwater Analytics (CWAN)'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating sharply across late 2025 and early 2026, with multiple consecutive quarters of substantial year-over-year gains. Annualized recurring revenue expanded materially over the same periods, reinforcing momentum.
Customer Loyalty & Retention: Client relationships appear sticky, with strong gross retention and ongoing net expansion across the base. Management also notes over 2,500 clients by year-end 2025, pointing to low churn and healthy upsell.
Healthy Cash Flow: Operating cash flow is described as strong alongside rising adjusted EBITDA with healthy margins. These trends suggest increasing capacity to fund integration and platform investments.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising briskly, with the latest quarter up year over year and full‑year FY2026 guidance raised for both revenue and ARR. Prior billings and deferred revenue growth indicate healthy demand heading into FY2026.
Strong Market Position & Advantage: Independent analyst evaluations place the company as a leader in SSE/SASE and note frequent inclusion on enterprise shortlists. A broad global footprint and regulatory certifications bolster competitiveness in regulated and international markets.
Product Line Growth: Expansion in newer offerings—such as Data Security, AI‑focused modules, and Zero Trust Branch—shows meaningful traction. Metered, non‑seat‑based solutions accounted for a sizable share of new ACV, suggesting broader monetization beyond core seats.
JumpCloud’s mission is to Make Work Happen®, providing simple, secure access to an organization’s technology resources from any device, or any location. The JumpCloud Open Directory Platform gives IT, security operations, and DevOps a single, cloud-based solution to control and manage employee identities and their devices, and apply conditional access controls based on Zero Trust principals. Since launching in 2012,...
JumpCloud's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is estimated to have reached about $105M in 2023, up from roughly $80M in 2022, indicating momentum through that period.
Product Line Growth: Regular 2026 releases and platform enhancements, along with acquisitions such as Resmo (2024) and VaultOne (2025), expanded capabilities into SaaS/asset visibility and PAM. This cadence also includes device and identity features like phishing‑resistant authentication.
Market Expansion: Expansion moves include opening a data center in India in 2026 and broader international build‑out across multiple countries, signaling investment in regional growth and compliance.
HERE Technologies is a location data and technology company that created the first digital map over 35 years ago. Today we are the world's leading location platform company with a global footprint across 52 countries. Although our strongest presence is in the automotive industry, we also work with leading companies across a wide range of industries, including transport and logistics,...
HERE Technologies's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent indices (e.g., Omdia 2025 and Counterpoint 2026) consistently place HERE at the top, highlighting strengths in AI mapping, sensor fusion, and business performance/orderbook. A steady cadence of launches and OEM deployments reinforces leadership in automotive‑grade location platforms.
Strategic Partnerships: Multi‑year alliances and expansions with AWS (10‑year, $1B), Esri (three‑year), and major OEMs such as JLR and Hyundai AutoEver, plus a Baidu Maps MoU, signal deepening commercial channels and long‑term demand. These collaborations span AI‑powered mapping, SDV tooling, and enhanced in‑vehicle experiences across regions.
Innovation-Driven Growth: AI‑powered mapping, SDV toolchains, and new offerings like GIS Data Suite and Location Reasoning indicate an active product engine aligned to growth areas. Added credentials such as AWS AI Competency and ISO/IEC 42001 for AI management support enterprise adoption.
.png)
Applied is the connective intelligence transforming how insurance works. We build the platforms, data, and agentic systems that connect the entire insurance journey, turning months of manual work into moments. We keep work flowing, from thousands of agencies and carriers to the millions of policyholders they protect.
Applied Systems's Top Stability & Growth Strengths
Strong Revenue Growth: S&P Global Ratings described multi‑year revenue growth with continued expansion expected, and inclusion on the 2026 Inc. 5000 points to sustained momentum. Company materials also cite a long‑run growth rate and record trading and adoption metrics in 2024–2025.
Innovation-Driven Growth: New AI‑driven capabilities in 2026 and the acquisitions of Planck (2024) and Cytora (2025) expand automation across intake, underwriting, reconciliation, and quoting. Ongoing enhancements across Epic and EZLynx and initiatives like an agentic email‑to‑quote channel indicate active product investment and monetization.
Strong Market Position & Advantage: Adoption signals include standardization by many top brokers, record attendance at Applied Net 2025, and recognition on G2 in 2026. Customer case examples and ecosystem reach reinforce a durable position in the independent‑agency software market.

Bounteous is a global AI Services firm where agentic engineering and human experience converge to deliver transformative business outcomes for the enterprise. We help organizations design, build, and scale AI-driven products, platforms, and processes. With more than 5,000 team members worldwide, Bounteous delivers AI that sticks, powering adoption and outcomes that move organizations from experimentation to true transformation.

Bounteous's Top Stability & Growth Strengths
Market Expansion: The merger with Accolite in 2024, global rebrand in 2025, and the 2026 Cartesian acquisition broadened footprint across North America, Europe, and India. Leadership appointments to run the India practice indicate continued investment in global delivery capacity.
Innovation-Driven Growth: The Cartesian deal was positioned to accelerate enterprise AI capabilities, and joining Anthropic’s Claude Partner Network signals an AI-led services push. Feedback suggests these moves deepen data and analytics strengths rather than retrenchment.
Strategic Partnerships: Recent partner accolades such as Acquia’s 2024 North America Partner of the Year and broader ecosystem momentum point to healthy demand and platform depth. Alliances highlighted across AI and digital experience stacks support go-to-market expansion.
Nexthink is the global leader in digital employee experience management. Our platform empowers IT teams with real-time visibility, analytics, and automation to proactively detect and resolve issues across any application, device, or network—before they affect employees. By shifting IT from reactive problem-solving to continuous optimization, Nexthink enables more than 1,300 organizations to create productive, seamless, and satisfying digital workplaces for...

Nexthink's Top Stability & Growth Strengths
Strong Market Position & Advantage: Repeated Leader placements in Gartner’s DEX Magic Quadrant (2024–2026) and Forrester’s 2024 EUEM Wave indicate durable competitive standing and sustained category momentum. These recognitions coincide with communications citing 1,200–1,500+ customers and 20M+ endpoints, underscoring broad enterprise adoption.
Product Line Growth: New offerings such as Adopt on Infinity (2025) and the Spark personal IT agent (2026), plus integrations like GoTo/Rescue and a government-focused AWS Marketplace listing, expand use cases and routes to market. The 2024 acquisition of AppLearn further broadened capabilities into digital adoption.
Investor Backing & Capital Strength: A late‑2025 majority investment by Vista Equity Partners at an approximately $3B valuation signals strong external confidence and provides resources for scaling. This step-up from the 2021 round supports continued product and go‑to‑market execution.

Join. Grow. Lead the Future of Supply Chain. At Cleo, we don’t just integrate supply chains—we orchestrate them. As the pioneer and global leader of the Supply Chain Orchestration software category, Cleo is helping thousands of companies around the globe drive transformation, deliver excellence, and shape the future of their global operations. Whether you're joining us from outside or growing within, Cleo...

Cleo's Top Stability & Growth Strengths
Customer Loyalty & Retention: Customer base and renewals are repeatedly cited on the site, indicating a large and sticky installed footprint. Feedback suggests thousands of active customers with strong renewal tendencies support stable, recurring revenue.
Strong Revenue Growth: Cloud subscription revenue was reported to have grown strongly for multiple consecutive years through 2022, with momentum indicated into 2023. These multi‑year gains point to durable expansion in the core subscription business.
Product Line Growth: The February 2025 acquisition of DataTrans Solutions added procurement‑automation and supplier‑enablement capabilities. This broadened platform scope supports larger use cases and potential cross‑sell into the existing base.